Profitable Betting Is Arithmetic First, Then Access
Edge without access is a spreadsheet. Work out whether your own number actually beats the price first; the route that lets you stake it comes after.
Profitable betting is arithmetic before anything else. An edge is your own estimate of how often a selection wins, multiplied against the price on offer; expected value (EV) is what is left once 1 is taken away, and a positive EV means the price pays more than your number says it should. Kelly staking turns that EV into a stake size, scaled to a bankroll rather than a fixed amount; half Kelly is the usual default, trading some average growth for a smoother run. None of that proves the estimate was right, and most bettors lose money over a long run even with careful records. What the maths cannot fix is access: a stake cut the moment you look sharp, or an exchange your account cannot reach. The worked numbers below use one set of odds throughout, so every figure can be checked by hand.
A search that usually gets the wrong answer first
Type "how to be profitable at sports betting" into a search box and most of what comes back sells a feeling: discipline, confidence, a system. None of it opens with a number. This page does the opposite: one set of odds, one probability, run through the same sums a broker's own calculator runs, before a single word about where to open an account.
This page sits inside this site's professional-betting section, and it assumes you already know what separates a sharp bettor from a lucky one. If that distinction means nothing yet, that page is the better place to start; everything below builds on it rather than repeating it.
A hunch is not a probability.
Turning that hunch into a number, testing whether the number survives contact with a real price, and sizing a stake against it only once it does: that is the order this page keeps, and it is a duller order than most search results promise.
Edge, in one line
Multiply your own probability by the price, take away 1, and whatever is left is expected value. At odds of 2.00, a 55% estimate gives EV of 0.55 × 2.00 − 1, which is +10%; a 45% estimate at the same price gives −10%. The sign matters more than the size: positive means the price pays more than your number implies it should, negative means the opposite, and the size only becomes a stake once Kelly does something with it, covered further down this page and by the calculator behind these numbers.
- It does not prove your probability was accurate, only that it is internally consistent with the price you compared it to.
- It does not mean anything from a single bet; it needs a long run before luck stops explaining the gap.
- It does not yet include what a broker's own exchange commission, or a bookmaker's built-in margin, will take back out of it.
One set of numbers, worked in full
Odds of 1.95, no exchange commission taken off yet, and your own read on the match puts the true chance at 54%, a plain view rather than anything special about this particular game.
EV = (0.54 × 1.95) − 1 = 1.053 − 1 = +5.3%. That is the number a positive-EV bettor is chasing: the price pays 5.3% more than 54% implies it should, assuming 54% is right.
Kelly turns that 5.3% into a stake size by dividing EV by the odds minus 1: 0.053 ÷ 0.95 = 5.58% of a bankroll, full Kelly. Half Kelly halves it to 2.79%, the more common choice because it gives up some average growth for a run with fewer sharp swings. On a bankroll of £1,500 that is £83.70 at full Kelly and £41.85 at half.
Half Kelly, 2.79% of the bankroll, staked again after every result rather than as a fixed amount: a win multiplies the bankroll by 1 + (0.0279 × 0.95) = 1.026505, a loss multiplies it by 1 − 0.0279 = 0.9721. Compounding, not flat stakes, because that is what the Kelly fraction actually describes.
Side note: the man the fraction is named after was not thinking about betting slips at all. John Kelly worked at Bell Labs in the 1950s on how fast information could travel down a noisy phone line without errors piling up, and the same maths turned out to describe how fast a bankroll grows under a repeated edge. Ed Thorp is the one who later took the same idea from card games to a hedge fund. Anyway, back to the twenty bets.
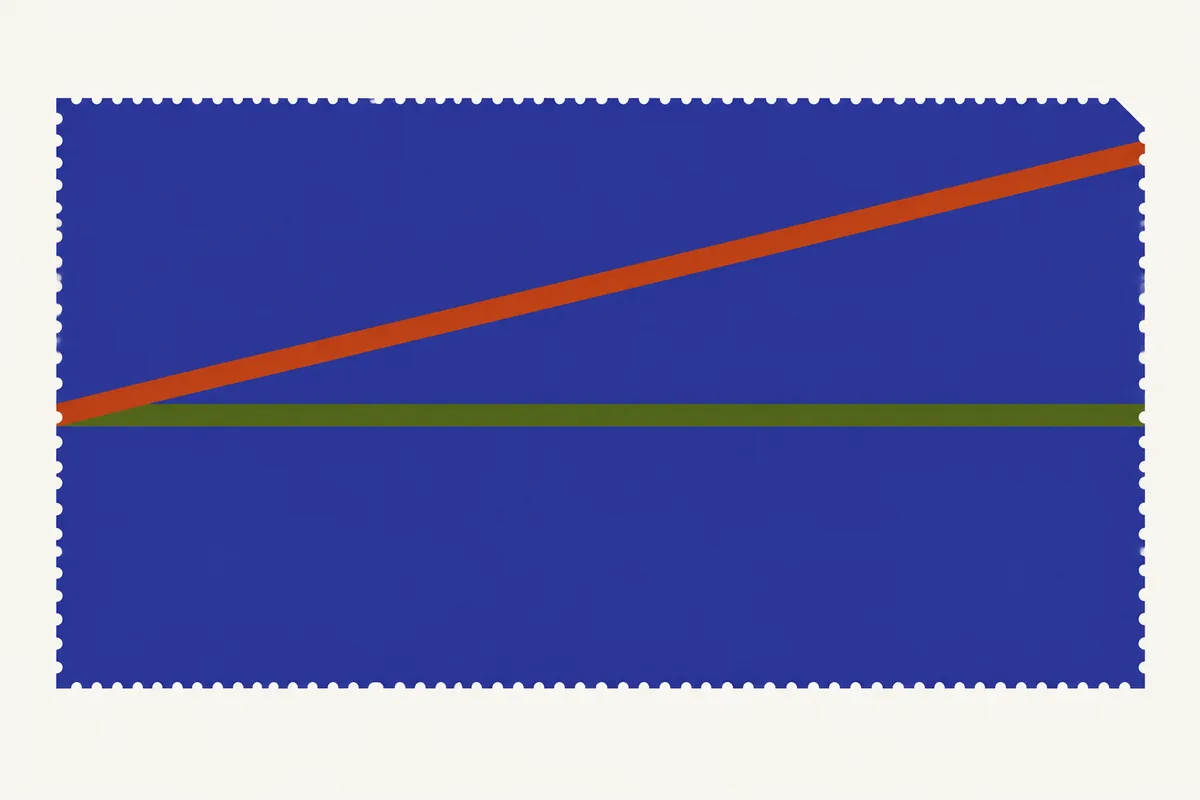
Walk that stake through twenty bets at these odds and the picture gets more honest than a single EV figure suggests. Take a fixed sequence with eleven wins and nine losses, a realised rate of 55%, close to the 54% assumed above (an exact 54% is not reachable over an integer count of twenty bets). Set beside it a second fixed sequence with ten wins and ten losses, a realised rate of 50%, close to the 51.28% that odds of 1.95 imply as fair, the rate at which there is no edge at all.
Twenty bets will not separate a real edge from a lucky run; the chart exists to show that even a favourable fixed sequence spends part of its run behind where it started. Whether 54% was ever the right number to type in is a separate question: spotting a price that was actually wrong covers it.
The stake size is solved arithmetic. The probability is still a guess.
Run your own numbers instead of mine
Everything above came from the calculator: type in odds, a probability and, if the price sits on an exchange, a commission rate, and it returns the effective price, EV and a Kelly stake at full, half and quarter.
The calculator's own two reference examples use different numbers from mine on purpose, so the two sets are never confused with each other. No exchange commission, odds of 2.10 at a 55% estimate: EV +15.5%, full Kelly 14.09%, half Kelly 7.05%, which is £70.45 of a £1,000 bankroll. Tick the exchange box at odds of 2.20, a 2% commission and a 50% estimate, and the effective price drops to 2.176: EV +8.8%, full Kelly 7.48%, half Kelly 3.74%, £74.80 of a £2,000 bankroll.
What the tool does and does not do matters. It sizes a stake for an edge you already believe you have; it does not go looking for one, and a positive figure is not the calculator agreeing with your read of the match, only doing the one job it has on whatever number you handed it.
The part most "how to be profitable" pages skip
The twenty-bet chart already showed a favourable fixed sequence spending part of its run behind where it started. Stretch the same idea across a season and the swings shrink but never disappear: a genuine edge shows in the long-run average, not in one short stretch, and judging an edge by the last fortnight is measuring noise.
Bankroll size is the other half of surviving that noise, and it is not repeated here. The bankroll and record-keeping side of turning pro works through how large a bankroll needs to be, in stakes rather than currency, before an edge has had time to prove itself against bad luck alone.
Edge finds the price. Access decides whether you get it.
A positive EV on paper is worth nothing if the account that could stake it gets capped the week results start looking non-random, or was never open to that account in the first place. That is why a book caps a winning account to begin with, and it is a different problem from anything the calculator above can solve.
Not every price worth checking sits on a simple win-or-lose line either; a handicap line that settles in halves needs its own read before this EV maths applies cleanly. Much of the watching this method needs, price alerts and side-by-side odds screens, already sits inside a broker's own platform: the alert and odds-screen tools already built in cover it. For anyone who would rather not stake on a probability typed in by hand, locking a result across two venues instead is the other method covered here, with its own arithmetic and its own frictions.
- Exchange commission, taken off every winning bet and none of the losing ones, which narrows every EV figure on this page the moment it applies.
- A country list the broker sets for itself, separate from wherever Betfair or a sportsbook draws its own line.
- A minimum stake that does not divide evenly once a bankroll is split across two or three venues.
- Turnover rules that apply to a withdrawal whether the balance came from a real edge or from a lucky month.
- ID checks before the first withdrawal, whatever the size of the deposit that started the account.
- A broker's own discretion to review an account once it shows an unusual pattern of results, win or lose.
Four brokers sell a route into an exchange, and each one's commission sits inside every EV number above once a bet is placed through it. BetInAsia's current pages print no commission figure for Sharp Exchange at all, so check the current terms before assuming an older 2.5% still holds, and its own list turns away the UK, the USA, France and more besides. AsianConnect's OrbitX and PIWIX exchange tools may also charge 3% on winning bets, and PIWIX drops lay betting on horse racing specifically, so that market needs a different route regardless of the edge. MadMarket's Sharp Exchange states a flat 3% on winning bets, nothing on losing ones, and excludes the UK, the USA and Australia by its own list, not for you if you live in any of those. Sportmarket's FairExchange charges 3% on winning bets only, and excludes the UK, the USA and France.
See where each broker actually sits on cost and coverage before funding one for this specific purpose; exchange commission is only one line in that comparison.
Who this actually suits
Someone who already has a number, in writing, before the bet goes on, not after. Everyone else should read the mechanism above twice before opening a broker account for this reason.
None of the arithmetic on this page is complicated. Keeping it honest over hundreds of bets, with the same discipline the twenty-bet chart only hints at, is the actual difficulty, and it has very little to do with which broker a stake ends up going through.